The Effect Of A Personal Bankruptcy On Your Credit
Content create by-Kaya Terry
Filing for personal bankruptcy is a significant decision that should not be made lightly. There are many things that you need to know before you do so to make sure that the process has the best possible outcome for you and your family. Keep reading to learn more about the bankruptcy process.
Do not attempt to conceal https://www.gov.uk/government/news/student-housing-investors-jailed-after-ponzi-scheme-defrauds-clients when filing for bankruptcy because you may be penalized when they are discovered. Whoever provides your legal consultation must be privy to all of your financial information. Never hide anything, and make sure you come up with a well devised plan for dealing with bankruptcy.
Many people do not know that student loans are not dischargeable debt under bankruptcy laws. Do not go into your bankruptcy thinking that your student loans will be discharged, because only in cases of extreme hardship are they considered. If the job you received from pursuing your degree will never allow you to pay off your debt, you may have a chance, but it is highly unlikely.
A useful tip for those thinking about filing for personal bankruptcy is, to keep in mind that any damage to your credit history caused by the filing is temporary. While there is no doubt that your score will take a noticeable hit, following your bankruptcy discharge, by using the process to start fresh. You have the ability to put yourself on a stronger financial footing going forward. This will allow you to rebuild your credit score faster than you may expect.
Filing for bankruptcy will not only just stop credit card companies from harassing you about debt. It will wipe out many of your debts, which may include utility company bills, wage garnishment and foreclosure. It will reduce all of these debts down to zero, and you will have to rebuild your credit all over.
If you have financial issues due to something like a drinking, drug, or gambling problem, get help instead of immediately filing for bankruptcy. You will continue to have financial issues if you have serious problems with, spending lots of money on these items. Try getting into counseling as soon as you can, to better your situation.
A great tip for filers of personal bankruptcy is to thoroughly prepare for the initial meeting with the bankruptcy attorney. By assembling every piece of relevant financial documentation, including mortgage documents, auto finance agreements, credit card statements, tax records and bank statements, you can be certain that your bankruptcy petition and supporting documentation includes all information required for a comprehensive filing.
Bankruptcy is something that is set up to help you. Do not think that your life is over because of bankruptcy. There will be some limitations to things that you can do, however, they are only temporary. There are also organizations out there that can help you get your life back in order after bankruptcy. If you filed or are thinking of filing, you should look into these organizations. There is hope.
Do some research about bankruptcy laws before filing for bankruptcy. For instance, somebody cannot transfer assets from a filer's name up to a year after they file. It's also prohibted to run up debt on credit cards just prior to filing.
https://www.livemint.com/opinion/online-views/opinion-a-quicker-resolution-of-bad-debts-in-sight-now-1548609546335.html before time runs out to avoid harsh penalties. If you wait too long to file, you may be forced to pay fees through garnishments taken from your bank accounts, foreclosure or even through wages. Early filing can also help prevent extensive reviews of your bankruptcy filing qualifications that may disqualify you.
Before opting to file for personal bankruptcy, try to pay off all of your debts. Some creditors are more than willing to work with you and you should do so before deciding to file for bankruptcy. This way, you can avoid all of the problems that are associated with bankruptcy.
When it comes to personal bankruptcy, be sure that you do not believe that all of your credit card balances will be eliminated. This is important to know because you do not want to find yourself in a worse situation than you are already in. Make sure all of your debts are accounted for.
Filing for bankruptcy doesn't mean you will lose all your assets. Personal property can be kept. This may be things like jewelry, clothing, furniture and electronics. The laws of your state and the kind of bankruptcy for which you are filing, coupled with your financial situation, will determine what personal property you are allowed to retain. Additionally, the retention of large assets, such as your automobile and your home, is determined by these considerations.
Do not allow future creditors to charge you ridiculously high interest rates due to a past bankruptcy. If it has been more than two years since the bankruptcy and you have been doing well since you filed, then you are eligible to receive a loan at whatever the going interest rate is at the time.
If you are avoiding personal bankruptcy but fear that you will lose your retirement savings, you should know that is not likely to happen. If you have an ERISA qualified retirement program (most are), then your retirement savings are safe from claims by creditors. This applies to funds in 401ks and to most IRAs. Consult your own bankruptcy attorney for specific details for your circumstances, but you should know the odds are in your favor.
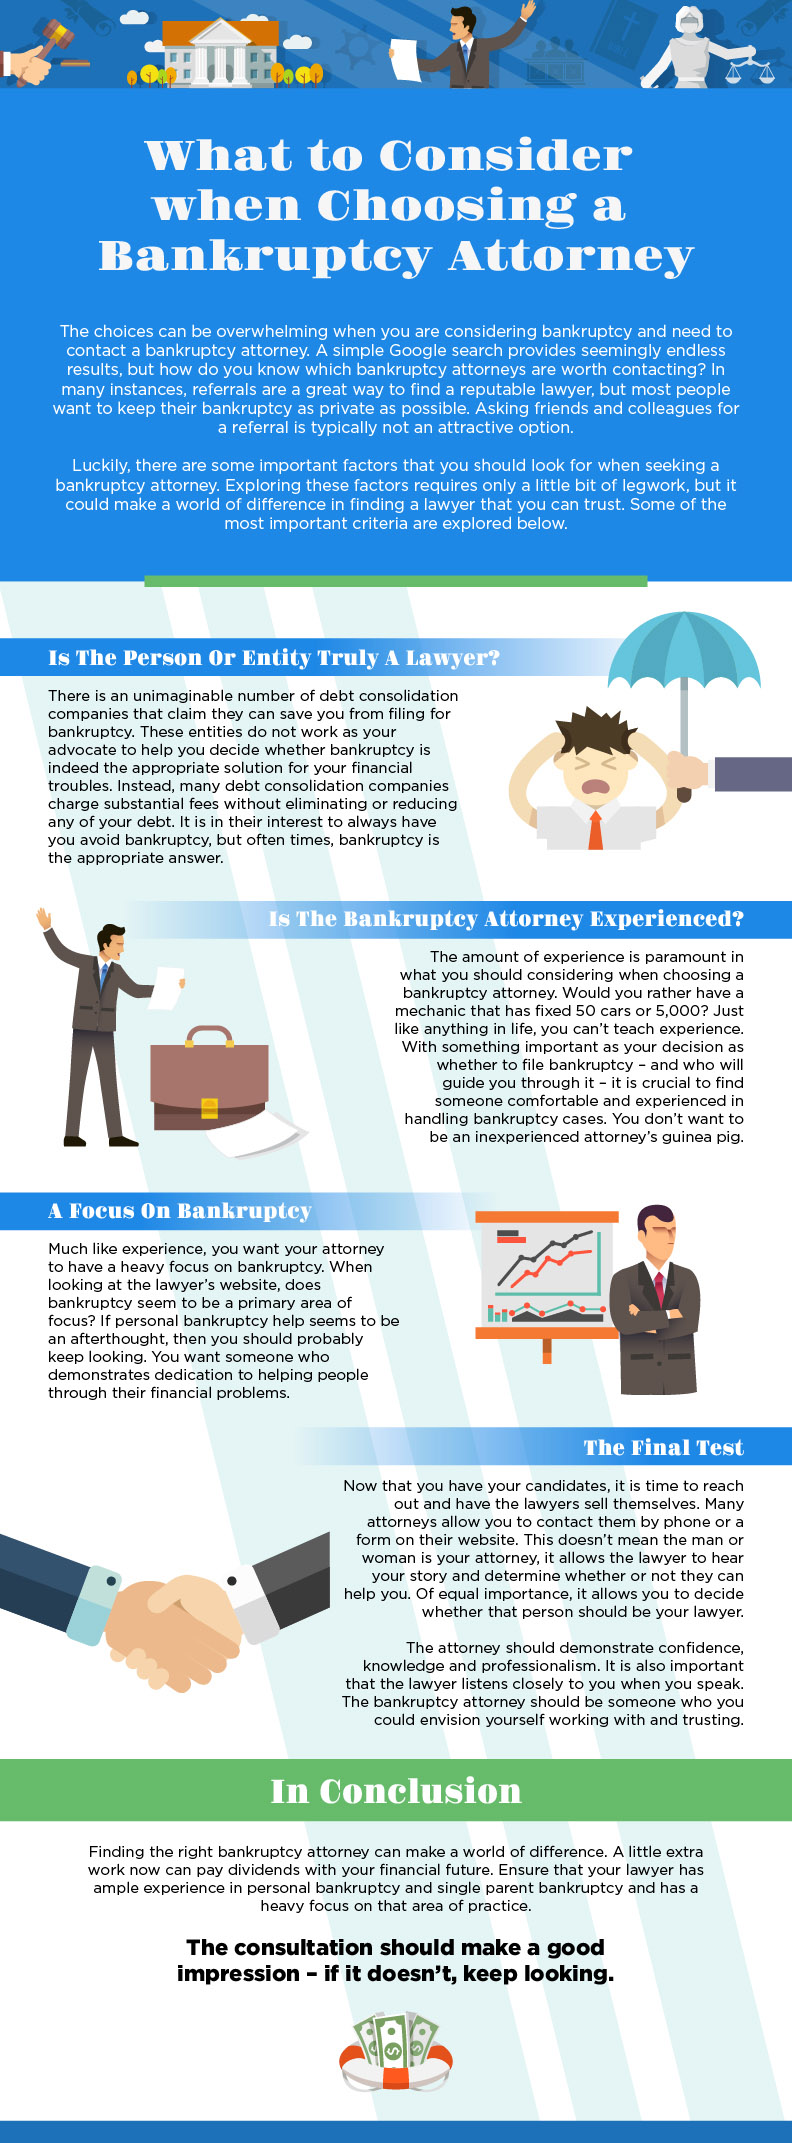
If you think you have to file a petition for bankruptcy, get a lawyer who specializes in bankruptcy. A qualified attorney can advise you on the necessity of filing, represent you in court and simplify a complex process. They can also help to unravel the complexities of the paperwork and give you any further information you need.
When you meet with your lawyer, bring along all of your financial records. Your lawyer will want to see loan documents from your car and house. They will also want to see your credit card bills and any other financial documents you have that show you are in debt. You will also need to bring any documents showing your assets.
If you are filing for chapter seven bankruptcy, the dismissal of the balance of your debts is not a given. There are secured debts that must be reaffirmed, meaning you must draw up a new payment agreement. Other debts cannot be discharged at all. For instance, court-sanctioned fines cannot be discharged under Chapter 7. The same goes for child support and alimony payments.
As you are no doubt aware, the decision to file for personal bankruptcy can be a difficult one. If you have resolved to take this step, however, you need to be familiar with the process, so that it will go as smoothly as possible for you. Remember the advice from this article and you will have a better outcome.
Filing for personal bankruptcy is a significant decision that should not be made lightly. There are many things that you need to know before you do so to make sure that the process has the best possible outcome for you and your family. Keep reading to learn more about the bankruptcy process.
Do not attempt to conceal https://www.gov.uk/government/news/student-housing-investors-jailed-after-ponzi-scheme-defrauds-clients when filing for bankruptcy because you may be penalized when they are discovered. Whoever provides your legal consultation must be privy to all of your financial information. Never hide anything, and make sure you come up with a well devised plan for dealing with bankruptcy.
Many people do not know that student loans are not dischargeable debt under bankruptcy laws. Do not go into your bankruptcy thinking that your student loans will be discharged, because only in cases of extreme hardship are they considered. If the job you received from pursuing your degree will never allow you to pay off your debt, you may have a chance, but it is highly unlikely.
A useful tip for those thinking about filing for personal bankruptcy is, to keep in mind that any damage to your credit history caused by the filing is temporary. While there is no doubt that your score will take a noticeable hit, following your bankruptcy discharge, by using the process to start fresh. You have the ability to put yourself on a stronger financial footing going forward. This will allow you to rebuild your credit score faster than you may expect.
Filing for bankruptcy will not only just stop credit card companies from harassing you about debt. It will wipe out many of your debts, which may include utility company bills, wage garnishment and foreclosure. It will reduce all of these debts down to zero, and you will have to rebuild your credit all over.
If you have financial issues due to something like a drinking, drug, or gambling problem, get help instead of immediately filing for bankruptcy. You will continue to have financial issues if you have serious problems with, spending lots of money on these items. Try getting into counseling as soon as you can, to better your situation.
A great tip for filers of personal bankruptcy is to thoroughly prepare for the initial meeting with the bankruptcy attorney. By assembling every piece of relevant financial documentation, including mortgage documents, auto finance agreements, credit card statements, tax records and bank statements, you can be certain that your bankruptcy petition and supporting documentation includes all information required for a comprehensive filing.
What Happens When Your Credit Card Company Sues You?
What Happens When Your Credit Card Company Sues You? Ignoring debt collection calls usually doesn't make them go away. Ignore your credit card debt long enough, and your credit card company may sell your account to a collection agency or sue you in civil court for the balance. While it's best to try to work with your credit card company before a lawsuit is filed, it's also important to know what to expect if you receive a summons and how you can respond to it.
Bankruptcy is something that is set up to help you. Do not think that your life is over because of bankruptcy. There will be some limitations to things that you can do, however, they are only temporary. There are also organizations out there that can help you get your life back in order after bankruptcy. If you filed or are thinking of filing, you should look into these organizations. There is hope.
Do some research about bankruptcy laws before filing for bankruptcy. For instance, somebody cannot transfer assets from a filer's name up to a year after they file. It's also prohibted to run up debt on credit cards just prior to filing.
https://www.livemint.com/opinion/online-views/opinion-a-quicker-resolution-of-bad-debts-in-sight-now-1548609546335.html before time runs out to avoid harsh penalties. If you wait too long to file, you may be forced to pay fees through garnishments taken from your bank accounts, foreclosure or even through wages. Early filing can also help prevent extensive reviews of your bankruptcy filing qualifications that may disqualify you.
Before opting to file for personal bankruptcy, try to pay off all of your debts. Some creditors are more than willing to work with you and you should do so before deciding to file for bankruptcy. This way, you can avoid all of the problems that are associated with bankruptcy.
When it comes to personal bankruptcy, be sure that you do not believe that all of your credit card balances will be eliminated. This is important to know because you do not want to find yourself in a worse situation than you are already in. Make sure all of your debts are accounted for.
Filing for bankruptcy doesn't mean you will lose all your assets. Personal property can be kept. This may be things like jewelry, clothing, furniture and electronics. The laws of your state and the kind of bankruptcy for which you are filing, coupled with your financial situation, will determine what personal property you are allowed to retain. Additionally, the retention of large assets, such as your automobile and your home, is determined by these considerations.
Do not allow future creditors to charge you ridiculously high interest rates due to a past bankruptcy. If it has been more than two years since the bankruptcy and you have been doing well since you filed, then you are eligible to receive a loan at whatever the going interest rate is at the time.
If you are avoiding personal bankruptcy but fear that you will lose your retirement savings, you should know that is not likely to happen. If you have an ERISA qualified retirement program (most are), then your retirement savings are safe from claims by creditors. This applies to funds in 401ks and to most IRAs. Consult your own bankruptcy attorney for specific details for your circumstances, but you should know the odds are in your favor.
If you think you have to file a petition for bankruptcy, get a lawyer who specializes in bankruptcy. A qualified attorney can advise you on the necessity of filing, represent you in court and simplify a complex process. They can also help to unravel the complexities of the paperwork and give you any further information you need.
When you meet with your lawyer, bring along all of your financial records. Your lawyer will want to see loan documents from your car and house. They will also want to see your credit card bills and any other financial documents you have that show you are in debt. You will also need to bring any documents showing your assets.
If you are filing for chapter seven bankruptcy, the dismissal of the balance of your debts is not a given. There are secured debts that must be reaffirmed, meaning you must draw up a new payment agreement. Other debts cannot be discharged at all. For instance, court-sanctioned fines cannot be discharged under Chapter 7. The same goes for child support and alimony payments.
As you are no doubt aware, the decision to file for personal bankruptcy can be a difficult one. If you have resolved to take this step, however, you need to be familiar with the process, so that it will go as smoothly as possible for you. Remember the advice from this article and you will have a better outcome.
Replies