Suggestions On Exactly How To Declare Insolvency
Article writer-Thorup Kelly
Deciding to file for personal bankruptcy is a very serious decision to make. It will have repercussions that will follow you for the rest of your life. Bankruptcy laws are not easy for non-lawyers to understand, but the information in this article will help explain what bankruptcy is, and how it can benefit you.
Keep your debts to a minimum prior to filing. If you are planning on filing for bankruptcy, don't run up your debts. Your recent history will be checked by judges and creditors, and if it is deemed that you are trying to cheat the system, you may not be able to wipe out those debts. You will be viewed most favorably, if you can demonstrate that you have changed your spending habits.
After filing for bankruptcy, check your credit report to make sure that it was reported the way that it should have been. You want to make sure that any debts that were part of your bankruptcy are now labeled "BK" so creditors know you no longer owe that money.
Make sure that you pay all of your bills on time, since this will contribute to 35 percent of what is on your credit report. This looks good if you are trying to rebuild your credit after you have had to file for bankruptcy. Making on-time payments will increase your credit score.
Honesty may never have been as important as it will be when going through personal bankruptcy. Hiding income or assets may result in a dismissal from the court. http://www.mondaq.com/india/x/813810/Insolvency+Bankruptcy/RBI+Issues+Revised+Prudential+Framework+For+Resolution+Of+Stressed+Assets could also mean that you will be barred from ever having the opportunity to file for bankruptcy any time in the future.
After your bankruptcy is finalized, you should begin re-building your credit by, obtaining copies of your credit reports. Your reports may show that you filed for bankruptcy, but it can take a lot of time for the credit bureaus to remove the original debt from your credit history. Check your reports over thoroughly, if there is debt showing that was discharged in a bankruptcy, you can contact the credit bureaus online, or in writing and request that the information be deleted.
Be fully educated about the rules of bankruptcy. If the courts were to find that you have disregarded any of the rules in place, your petition could be dismissed. Laws prohibit picking and choosing some debts to pay off prior to filing for bankruptcy. Family members cannot be paid off within one year of filing and creditors are limited to ninety days.
Bankruptcy laws vary from state to state. Play it safe and hire an attorney that works in your own state to be sure that the correct laws are followed. Some lawyers are better than others, so be sure to select one that is qualified to handle your case. It could make a big difference in how smoothly things go and the end result.
Be sure your home is well protected. Filing for bankruptcy does not mean you have to lose your home. If your home has significantly depreciated in value or you've taken a second mortgage, it may be possible to retain possession of your home. You may also want to check out the homestead exemption because it may allow you to keep your home.
A good personal bankruptcy tip is to be absolutely sure that you've gone through all of your options before you decide to file for bankruptcy. If the amount you owe is relatively small, you can always try to negotiate it by working through a credit counselor and making small payments.
If you are planning to file for bankruptcy, you must seriously take into account anyone who has cosigned on a loan for you. For instance, if a friend or relative is a cosigner on your auto or home loan, they will be held financially responsible to pay the debt in the event you file for bankruptcy. This can create problems in relationships between family members and friends. That is why it is not advisable to cosign for anyone or ask someone to cosign for you, including your children. just click the following internet site could ruin someone's life.
After filing bankruptcy, many people refuse to use credit cards or get loans. However, this is not a good idea because it is desirable to heal your credit rating. Good credit is needed to make major purchases, such as those for homes and automobiles. However, if you don't use credit, you will be unable to establish a good credit history, which is necessary in order to make those purchases. Take it slow and get yourself one credit card and slowly rebuild your credit.
See what the value is on your home. If you are upside down on your mortgage, you may be able to eliminate your second mortgage. The main guideline for this is that your home must be worth more than what you owe on the first mortgage. This could really help your financial situation by relieving you from that large second mortgage payment each month.
Be completely honest when filing your bankruptcy schedules. You must disclose absolutely all of your debts and personal property, including tax refunds, child support, social security and other less-obvious assets and claims. Hiding your assets or claims is a federal crime, which can be punishable by loss of your claim or a prison sentence.
A good personal bankruptcy tip is to learn as much as you can, so that you can feel more at ease with filing for bankruptcy. A lot of people are reluctant to file for bankruptcy because they think they'll lose their jobs, but the law states that it's against the law for employers to terminate for that reason.
It is important to know that with personal bankruptcy, you still will be able to open a bank account. It is critical that you know this because it is actually somewhat easy to sign up for a free account with credit unions and banks. The only place that you might run into an issue is with a commercial account.
In order to file for bankruptcy, you'll need professional legal assistance. The earlier in the process you find legal counsel, the better. Do not worry about the expense of a bankruptcy attorney. Most lawyers who specialize in this field understand, your financial difficulties. The sooner you start taking advantage of their expert advice, the better off you will be.
Take note of any tip you found to be especially helpful here. Print a copy to keep on your desk as you prepare to file for personal bankruptcy. This will make it easy to benefit the most from the information learned here. It is the details that are missed that may hurt you the most, so be sure to be careful when filing.
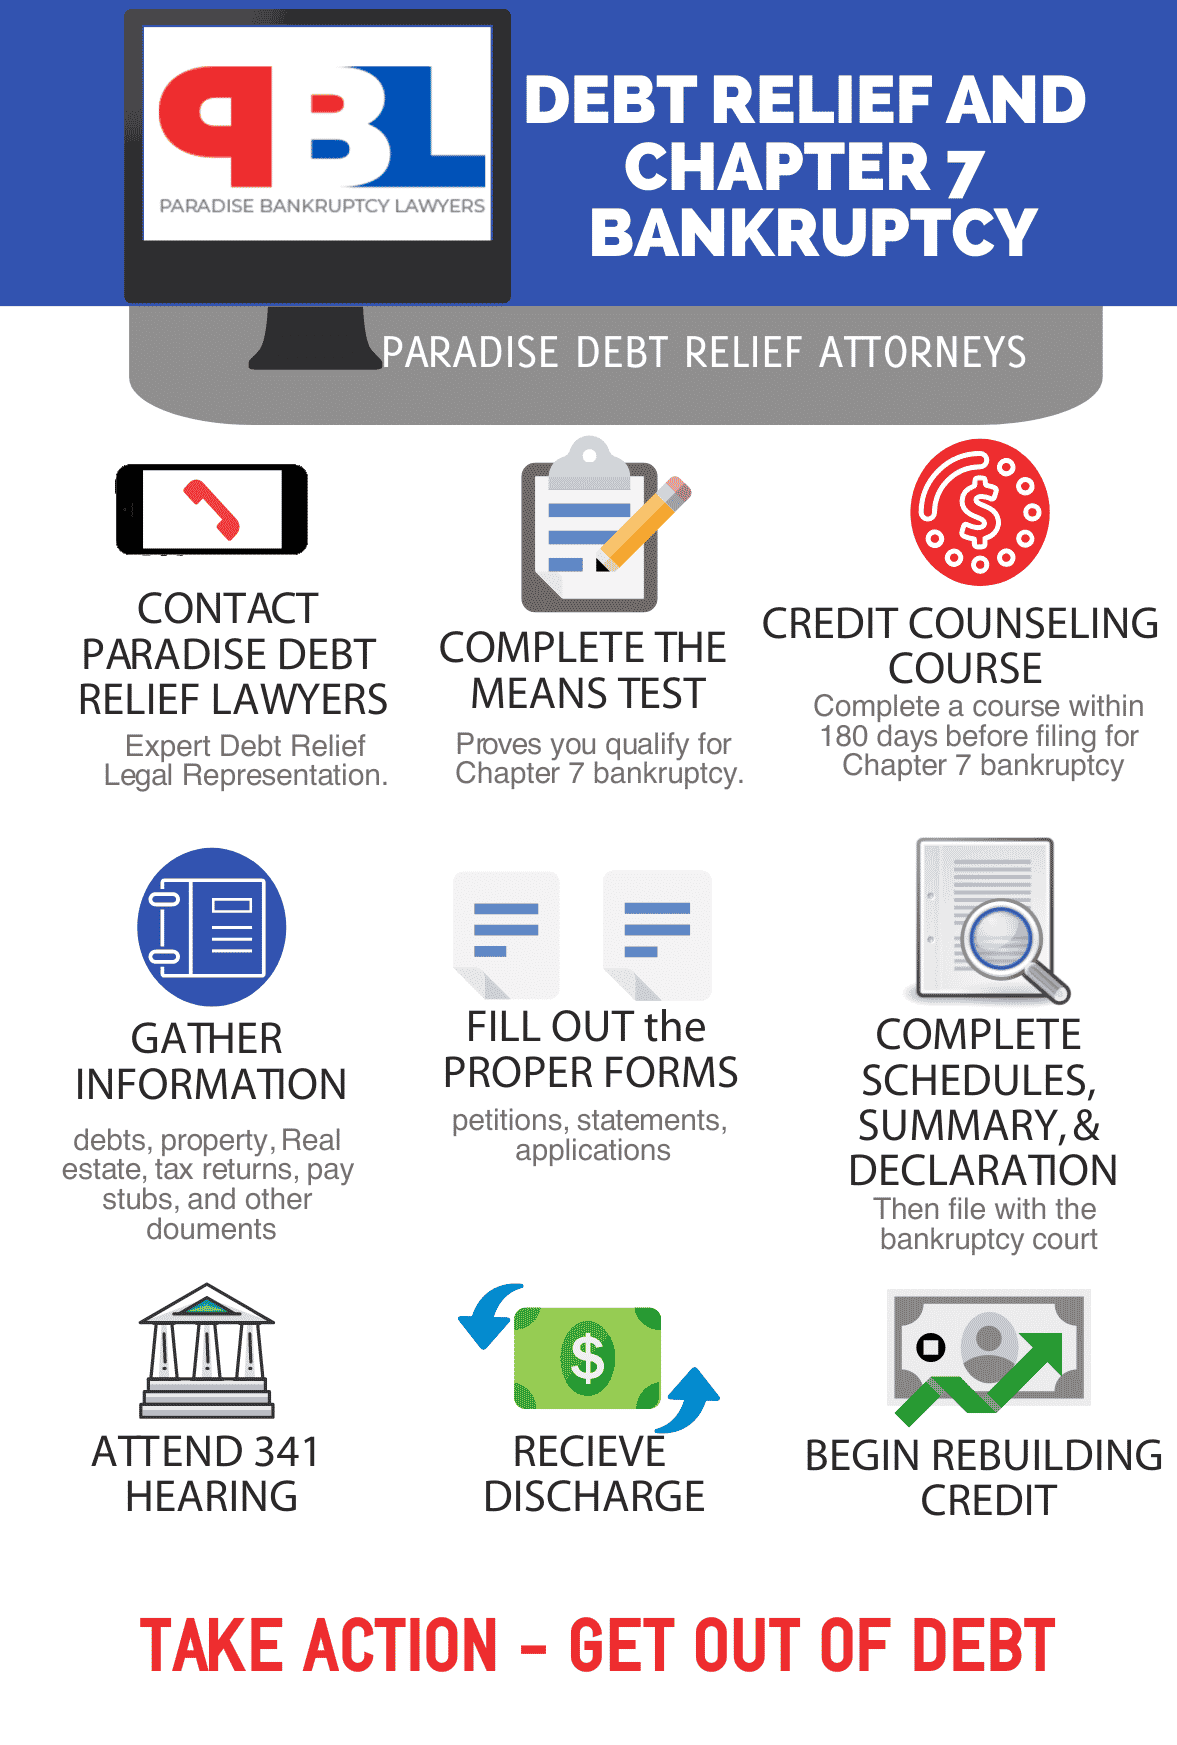
Deciding to file for personal bankruptcy is a very serious decision to make. It will have repercussions that will follow you for the rest of your life. Bankruptcy laws are not easy for non-lawyers to understand, but the information in this article will help explain what bankruptcy is, and how it can benefit you.
How You Can Get Your Student Loans Discharged In Bankruptcy
How You Can Get Your Student Loans Discharged In Bankruptcy It's important to note that bankruptcy judges, in general, want to hear your case. It's been heard from several judges at various conferences and events that they don't see enough student loan debt bankruptcy cases - which then limits their ability to create case law.
Keep your debts to a minimum prior to filing. If you are planning on filing for bankruptcy, don't run up your debts. Your recent history will be checked by judges and creditors, and if it is deemed that you are trying to cheat the system, you may not be able to wipe out those debts. You will be viewed most favorably, if you can demonstrate that you have changed your spending habits.
After filing for bankruptcy, check your credit report to make sure that it was reported the way that it should have been. You want to make sure that any debts that were part of your bankruptcy are now labeled "BK" so creditors know you no longer owe that money.
Make sure that you pay all of your bills on time, since this will contribute to 35 percent of what is on your credit report. This looks good if you are trying to rebuild your credit after you have had to file for bankruptcy. Making on-time payments will increase your credit score.
Honesty may never have been as important as it will be when going through personal bankruptcy. Hiding income or assets may result in a dismissal from the court. http://www.mondaq.com/india/x/813810/Insolvency+Bankruptcy/RBI+Issues+Revised+Prudential+Framework+For+Resolution+Of+Stressed+Assets could also mean that you will be barred from ever having the opportunity to file for bankruptcy any time in the future.
After your bankruptcy is finalized, you should begin re-building your credit by, obtaining copies of your credit reports. Your reports may show that you filed for bankruptcy, but it can take a lot of time for the credit bureaus to remove the original debt from your credit history. Check your reports over thoroughly, if there is debt showing that was discharged in a bankruptcy, you can contact the credit bureaus online, or in writing and request that the information be deleted.
Be fully educated about the rules of bankruptcy. If the courts were to find that you have disregarded any of the rules in place, your petition could be dismissed. Laws prohibit picking and choosing some debts to pay off prior to filing for bankruptcy. Family members cannot be paid off within one year of filing and creditors are limited to ninety days.
Bankruptcy laws vary from state to state. Play it safe and hire an attorney that works in your own state to be sure that the correct laws are followed. Some lawyers are better than others, so be sure to select one that is qualified to handle your case. It could make a big difference in how smoothly things go and the end result.
Be sure your home is well protected. Filing for bankruptcy does not mean you have to lose your home. If your home has significantly depreciated in value or you've taken a second mortgage, it may be possible to retain possession of your home. You may also want to check out the homestead exemption because it may allow you to keep your home.
A good personal bankruptcy tip is to be absolutely sure that you've gone through all of your options before you decide to file for bankruptcy. If the amount you owe is relatively small, you can always try to negotiate it by working through a credit counselor and making small payments.
If you are planning to file for bankruptcy, you must seriously take into account anyone who has cosigned on a loan for you. For instance, if a friend or relative is a cosigner on your auto or home loan, they will be held financially responsible to pay the debt in the event you file for bankruptcy. This can create problems in relationships between family members and friends. That is why it is not advisable to cosign for anyone or ask someone to cosign for you, including your children. just click the following internet site could ruin someone's life.
After filing bankruptcy, many people refuse to use credit cards or get loans. However, this is not a good idea because it is desirable to heal your credit rating. Good credit is needed to make major purchases, such as those for homes and automobiles. However, if you don't use credit, you will be unable to establish a good credit history, which is necessary in order to make those purchases. Take it slow and get yourself one credit card and slowly rebuild your credit.
See what the value is on your home. If you are upside down on your mortgage, you may be able to eliminate your second mortgage. The main guideline for this is that your home must be worth more than what you owe on the first mortgage. This could really help your financial situation by relieving you from that large second mortgage payment each month.
Be completely honest when filing your bankruptcy schedules. You must disclose absolutely all of your debts and personal property, including tax refunds, child support, social security and other less-obvious assets and claims. Hiding your assets or claims is a federal crime, which can be punishable by loss of your claim or a prison sentence.
A good personal bankruptcy tip is to learn as much as you can, so that you can feel more at ease with filing for bankruptcy. A lot of people are reluctant to file for bankruptcy because they think they'll lose their jobs, but the law states that it's against the law for employers to terminate for that reason.
It is important to know that with personal bankruptcy, you still will be able to open a bank account. It is critical that you know this because it is actually somewhat easy to sign up for a free account with credit unions and banks. The only place that you might run into an issue is with a commercial account.
In order to file for bankruptcy, you'll need professional legal assistance. The earlier in the process you find legal counsel, the better. Do not worry about the expense of a bankruptcy attorney. Most lawyers who specialize in this field understand, your financial difficulties. The sooner you start taking advantage of their expert advice, the better off you will be.
Take note of any tip you found to be especially helpful here. Print a copy to keep on your desk as you prepare to file for personal bankruptcy. This will make it easy to benefit the most from the information learned here. It is the details that are missed that may hurt you the most, so be sure to be careful when filing.
Replies