Solid Guidance On Filing For Personal Personal Bankruptcy
Content create by-Pickett Yildiz
Personal bankruptcy can be a scary situation for those who are facing repossession from the government and constant calls from debt collectors. If you find yourself in a hole that you cannot dig yourself out of, consider filing for personal bankruptcy. Read on for helpful tips on this situation.
You should look into and understand which debts are eligible to be written-off under bankruptcy. There are certain loans, such as student loans, that do not qualify. By understanding which debts you can write-off, you can make a better decision when trying to figure out if bankruptcy is the right choice for you.
You should look into and understand which debts are eligible to be written-off under bankruptcy. There are certain loans, such as student loans, that do not qualify. By understanding which debts you can write-off, you can make a better decision when trying to figure out if bankruptcy is the right choice for you.
Educate yourself about the bankruptcy process. You can increase your knowledge of the bankruptcy process by conversing with a bankruptcy attorney or by carrying out independent research on the internet. Whichever method you chose to increase your knowledge of the bankruptcy process, it is vital that you comprehend how filing for bankruptcy will affect yourself, your family and your creditors.
Find out as much as you can about the individual laws in your state. There is a lot of information about there, but every state has its particular laws that people are subject to. You may have a lawyer, but it is important that you know about this as well so you can make better decisions.
Meet with many different attorneys before making any decision on one. To do this, you must start looking well in advance of when you need to file. If you wait until the last minute, you will not have the time to find an attorney that will give you good advice, and one that is easy to work with.
Filing for bankruptcy will not only just stop credit card companies from harassing you about debt. It will wipe out many of your debts, which may include utility company bills, wage garnishment and foreclosure. It will reduce all of these debts down to zero, and you will have to rebuild your credit all over.
After the completion of filing for bankruptcy, get to work reestablishing your credit score. Keep in mind that thirty-five percent of the credit score is calculated using payment history. Keep your payments on time, because you will have to battle the bankruptcy on your report for the next ten years.
Fight the temptation to rack up large credit card balances just before filing. The creditor will take a look at your account history. If they determine that you charged a lot before applying for bankruptcy, they can file a request with the court to hold you responsible for the amount that you charged.
If you are going through a divorce and your ex-spouse files for bankruptcy, there are debts that cannot be discharged. Child support, alimony, many property settlement obligations, restitution, and student loans, are all not allowed to be discharged in a bankruptcy from divorce. In https://www.business-standard.com/article/companies/insolvency-woes-rcom-resolution-professional-asks-for-13-month-exclusion-119050701364_1.html , some property settlement agreements are allowed to be discharged. Consult with an attorney to find out which ones can.
Locate an online support forum for those who have filed for bankruptcy. This way, you can ask other people questions and find out things that you may not know. There are a lot of forums on the internet, but there are also, some offline groups you can join, if you prefer being offline. Because these people know what you're going through, they can make you feel better about the situation.
Don't make the mistake of hesitating to file for bankruptcy because you think you won't be able to file again and may need to save it for a worse financial situation. The laws vary from state to state, but you may file again after a certain period, usually two to eight years, depending on the type of bankruptcy filed. Of course, you won't want to file again, but in case of job loss or a major illness, the opportunity is there if you need it.
Do not be afraid to file for bankruptcy. Sometimes people find themselves so overwhelmed with debt that they just decide to do nothing and bury their heads in the sand. This is the worst thing that a person could possibly do. Instead, they should file for bankruptcy because by doing so, they are taking positive affirmative action and giving themselves another chance at managing their finances.
Many times people feel forced into filing for bankruptcy. They do not know that debt settlements are available. If your debt is much greater than your income, you could be a candidate for a debt settlement. Many times credit counselors can negotiate with banks and credit card companies to reduce the amount you owe, so that you do not have to file bankruptcy.
If you are in a financial position where declaring bankruptcy is imminent, never put off declaring. When https://www.business-standard.com/article/pti-stories/resolution-plans-under-ibc-have-yielded-200-pc-of-liquidation-value-sahoo-119042600526_1.html wait, your financial situation is likely to continue to deteriorate and prove even more devastating. For this reason, when the financial hole that you have dug is too deep, it is smart to file sooner, rather than later.
Choosing a good lawyer is an important step in the process. This area of law attracts some inexperienced amateurs. Always confirm that your lawyer is highly experienced and licensed to handle a bankruptcy. Information on lawyers and their ratings by clients can be found on the Internet.
Take the time to choose a good bankruptcy lawyer. This kind of law is usually where inexperienced attorney's reside. Investigate the attorney you are considering hiring and review his references. The Internet can help you check a lawyer's disciplinary record, as well as client ratings and background information.
Hopefully, this article has addressed some of your more pressing questions and fears regarding filing for personal bankruptcy. Navigating your way through the legal process and coming away with any hope can be near impossible. You need to understand that this is a temporary situation that you are in the process of resolving, and better financial times lay ahead!
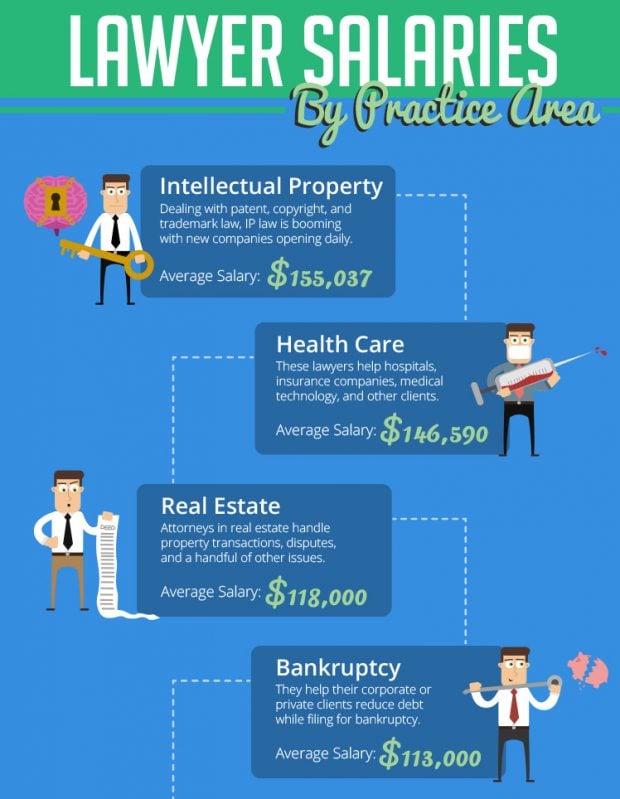
Personal bankruptcy can be a scary situation for those who are facing repossession from the government and constant calls from debt collectors. If you find yourself in a hole that you cannot dig yourself out of, consider filing for personal bankruptcy. Read on for helpful tips on this situation.
How Much Bankruptcy Costs and How to Pay for it
How Much Bankruptcy Costs and How to Pay for it We believe everyone should be able to make financial decisions with confidence. And while our site doesn’t feature every company or financial product available on the market, we’re proud that the guidance we offer, the information we provide and the tools we create are objective, independent, straightforward — and free.
You should look into and understand which debts are eligible to be written-off under bankruptcy. There are certain loans, such as student loans, that do not qualify. By understanding which debts you can write-off, you can make a better decision when trying to figure out if bankruptcy is the right choice for you.
You should look into and understand which debts are eligible to be written-off under bankruptcy. There are certain loans, such as student loans, that do not qualify. By understanding which debts you can write-off, you can make a better decision when trying to figure out if bankruptcy is the right choice for you.
Educate yourself about the bankruptcy process. You can increase your knowledge of the bankruptcy process by conversing with a bankruptcy attorney or by carrying out independent research on the internet. Whichever method you chose to increase your knowledge of the bankruptcy process, it is vital that you comprehend how filing for bankruptcy will affect yourself, your family and your creditors.
Find out as much as you can about the individual laws in your state. There is a lot of information about there, but every state has its particular laws that people are subject to. You may have a lawyer, but it is important that you know about this as well so you can make better decisions.
Meet with many different attorneys before making any decision on one. To do this, you must start looking well in advance of when you need to file. If you wait until the last minute, you will not have the time to find an attorney that will give you good advice, and one that is easy to work with.
Filing for bankruptcy will not only just stop credit card companies from harassing you about debt. It will wipe out many of your debts, which may include utility company bills, wage garnishment and foreclosure. It will reduce all of these debts down to zero, and you will have to rebuild your credit all over.
After the completion of filing for bankruptcy, get to work reestablishing your credit score. Keep in mind that thirty-five percent of the credit score is calculated using payment history. Keep your payments on time, because you will have to battle the bankruptcy on your report for the next ten years.
Fight the temptation to rack up large credit card balances just before filing. The creditor will take a look at your account history. If they determine that you charged a lot before applying for bankruptcy, they can file a request with the court to hold you responsible for the amount that you charged.
If you are going through a divorce and your ex-spouse files for bankruptcy, there are debts that cannot be discharged. Child support, alimony, many property settlement obligations, restitution, and student loans, are all not allowed to be discharged in a bankruptcy from divorce. In https://www.business-standard.com/article/companies/insolvency-woes-rcom-resolution-professional-asks-for-13-month-exclusion-119050701364_1.html , some property settlement agreements are allowed to be discharged. Consult with an attorney to find out which ones can.
Locate an online support forum for those who have filed for bankruptcy. This way, you can ask other people questions and find out things that you may not know. There are a lot of forums on the internet, but there are also, some offline groups you can join, if you prefer being offline. Because these people know what you're going through, they can make you feel better about the situation.
Don't make the mistake of hesitating to file for bankruptcy because you think you won't be able to file again and may need to save it for a worse financial situation. The laws vary from state to state, but you may file again after a certain period, usually two to eight years, depending on the type of bankruptcy filed. Of course, you won't want to file again, but in case of job loss or a major illness, the opportunity is there if you need it.
Do not be afraid to file for bankruptcy. Sometimes people find themselves so overwhelmed with debt that they just decide to do nothing and bury their heads in the sand. This is the worst thing that a person could possibly do. Instead, they should file for bankruptcy because by doing so, they are taking positive affirmative action and giving themselves another chance at managing their finances.
Many times people feel forced into filing for bankruptcy. They do not know that debt settlements are available. If your debt is much greater than your income, you could be a candidate for a debt settlement. Many times credit counselors can negotiate with banks and credit card companies to reduce the amount you owe, so that you do not have to file bankruptcy.
If you are in a financial position where declaring bankruptcy is imminent, never put off declaring. When https://www.business-standard.com/article/pti-stories/resolution-plans-under-ibc-have-yielded-200-pc-of-liquidation-value-sahoo-119042600526_1.html wait, your financial situation is likely to continue to deteriorate and prove even more devastating. For this reason, when the financial hole that you have dug is too deep, it is smart to file sooner, rather than later.
Choosing a good lawyer is an important step in the process. This area of law attracts some inexperienced amateurs. Always confirm that your lawyer is highly experienced and licensed to handle a bankruptcy. Information on lawyers and their ratings by clients can be found on the Internet.
Take the time to choose a good bankruptcy lawyer. This kind of law is usually where inexperienced attorney's reside. Investigate the attorney you are considering hiring and review his references. The Internet can help you check a lawyer's disciplinary record, as well as client ratings and background information.
Hopefully, this article has addressed some of your more pressing questions and fears regarding filing for personal bankruptcy. Navigating your way through the legal process and coming away with any hope can be near impossible. You need to understand that this is a temporary situation that you are in the process of resolving, and better financial times lay ahead!
Replies