Money Troubles? Find Out More Concerning Individual Personal Bankruptcy
Content by-Pearson Refsgaard
Personal bankruptcy can be a scary situation for those who are facing repossession from the government and constant calls from debt collectors. If you find yourself in a hole that you cannot dig yourself out of, consider filing for personal bankruptcy. Read on for helpful tips on this situation.
Don't let bill collectors convince you that you are ineligible for bankruptcy. Debt collectors do not want you to file bankruptcy under any circumstances because it means that they will not get the money you owe them, so they will always tell you that you do not qualify when given the chance. The only way to truly know if you qualify is to do some research or speak with a bankruptcy attorney.
Take some time each day to stop thinking about your bankruptcy. It can seem like a thought you cannot get out of your head, but it is important to step away from the situation before you become too upset. Not only that, but removing it from your thoughts allows you to bring a fresher, more optimistic perspective to the table when you take up the subject again.
Don't let bill collectors convince you that you are ineligible for bankruptcy. Debt collectors do not want you to file bankruptcy under any circumstances because it means that they will not get the money you owe them, so they will always tell you that you do not qualify when given the chance. The only way to truly know if you qualify is to do some research or speak with a bankruptcy attorney.
Look for a bankruptcy attorney that belongs to the NACBA (The National Association of Consumer Bankruptcy Attorneys). When you are filing for bankruptcy, it is essential that you hire the services of an experienced and reputable bankruptcy attorney. Attorneys that are members of the NACBA, are also, members of a well-respected consumer bankruptcy organization, so you can be sure that you will be getting the best legal advice available.
If you have student loan debt, you'll need to prove that paying your student loans would constitute an undue hardship in order to get it discharged. Gather visit the up coming website of your financial documents and draw up two budgets: one that includes student loan payments and one that does not. That way you can more easily demonstrate that paying your student loans would interfere with your financial recovery.
It is important that you don't let bankruptcy get you down in the dumps. Bankruptcy can be a challenging time in anyone's life, but it is meant to give you a fresh start, enabling you to establish good credit and move toward a better future for you and your family. Remember, bankruptcy is your legal right, so don't feel guilty or ashamed of taking advantage of it. If you do feel that you are suffering excess anxiety or depression over financial issues, counseling may help you to better deal with your emotions and concerns.
Ask friends and family for moral support. They may not be able to lend you money, but you should be able to tell them about your hardships and to lean on them. It can be hard to talk about money with the people close to you. You will likely find that they are much more supportive than you expect.
A great personal bankruptcy tip is to consider what kind of bankruptcy you'd like to go for. In general, chapter 13 is much better because it doesn't taint your credit report. It allows you to hold on to most of your belongings. Chapter 7 is much more extreme to file for.
When you are about to file for bankruptcy, be sure you have all the financial information at hand. Even things that you do not use, should be listed in a bankruptcy filing. These could include, income from even small jobs, any vehicles listed in the filer's name whether or not they use them, and any pending lawsuits.
Avoid running up your debt limit before you file for bankruptcy. Judges, and creditors look at recent history along with your current situation. A judge can deny some of your debts from being wiped out if, they think you're just taking advantage of the system. Try to show that that you're willing to change your fiscal habits.
Stay on top of your finances enough to file before the last possible moment. Your financial debt, and responsibilities will not solve themselves, nor will they be able to sit on the back burner forever. You must act decisively. Through knowledge of where your finances truly stand. Ignoring the problem will only result in greater issues.
Clean up your credit record after ten years. When you file Chapter 7 bankruptcy, it remains on your credit report for ten years. However, the credit bureaus are not required to remove the information. In order to get rid of the bankruptcy record, write a letter to the credit reporting agencies, along with a copy of your discharge notice. Follow https://www.thehindubusinessline.com/economy/logistics/creditors-panel-approve-jnpts-bid-to-buy-debt-laden-dighi-port/article26162798.ece up with a phone call to make sure that they have removed the bankruptcy record.
Get the details. After filing for personal bankruptcy, you are still obligated to pay your personal bills. The collection letters and some monthly bills will stop coming, but you are still required to pay them off. This means that even if you don't receive a bill to your house, it doesn't mean that you're off the hook!
No matter how trivial you may think it is, all income should be reported in your bankruptcy filing. You can create issues in your bankruptcy if your income information does not flush with bank and finance records. Be sure to include all incomes within the household that can be considered part of your normal income.
Many people think that they can save a lot of money by filing bankruptcy themselves and trying to handle their case without the aid of an attorney. This isn't wise for several reasons. There are up to 50 pages of paperwork to fill out, filings and laws that you may not know about. An attorney will know how to handle your case and will surely save you money by negotiating with your creditors.
Work with a reputable credit counseling agency. If you have decided to file for bankruptcy, work with a credit counseling agency that has the approval of the US Trustee's Office. They will provide a 90 minute mandatory counseling session, after which they will determine if you qualify for a Debt Management Plan. They will also issue you with a certificate that allows you to file for bankruptcy.
Avoiding bankruptcy is all about planning. Once you plan things out and execute your plan, you make sure that you are financially secure, no matter what comes up. Proper planning is key to making sure you are not stressed in life. Apply these tips to your life, so that you do not have to file for bankruptcy ever again.
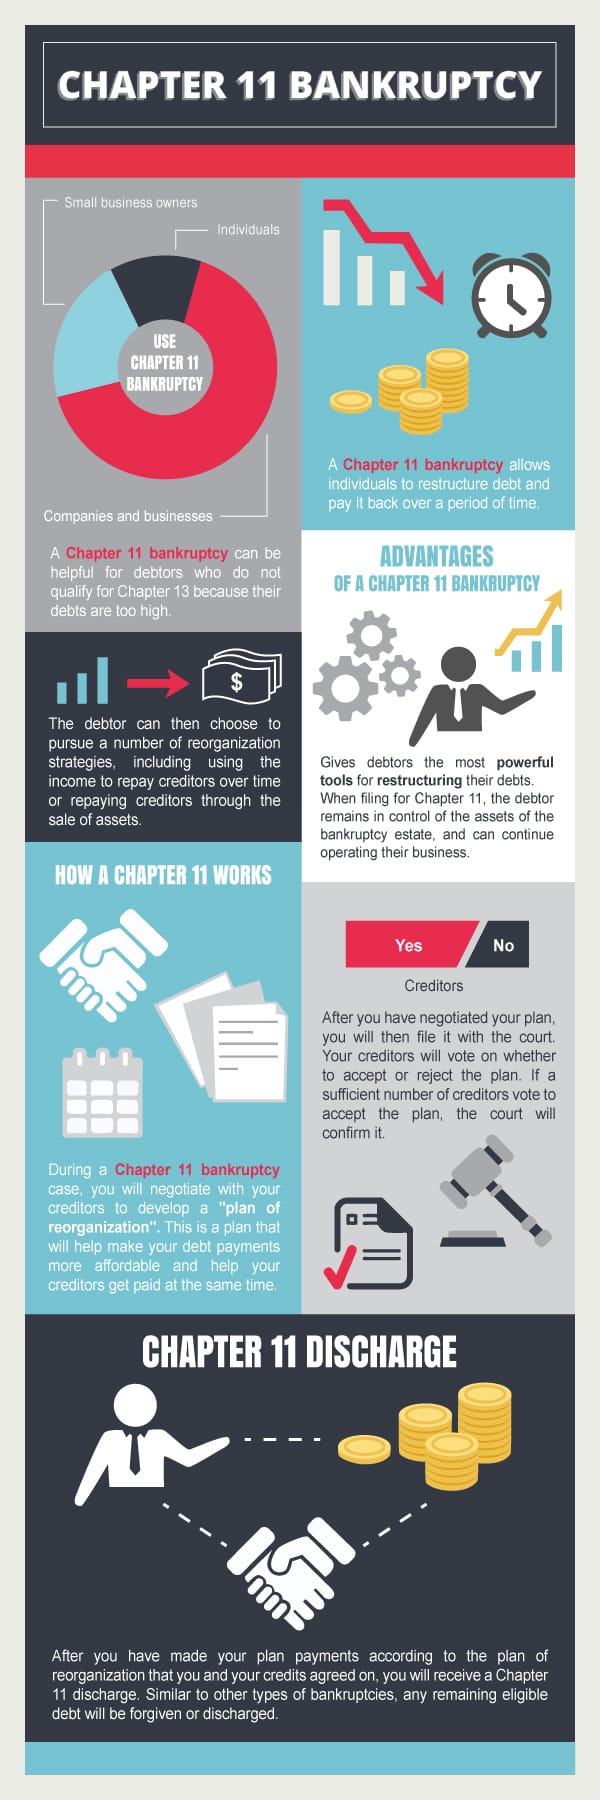
Personal bankruptcy can be a scary situation for those who are facing repossession from the government and constant calls from debt collectors. If you find yourself in a hole that you cannot dig yourself out of, consider filing for personal bankruptcy. Read on for helpful tips on this situation.
How Can I Tell Which Bankruptcy Solution is Right for Me?
How Can I Tell Which Bankruptcy Solution is Right for Me? Facing bankruptcy can be very intimidating and frightening. This is especially true when you consider the fact that you have multiple options, each of which is better suited to certain types of financial scenarios than to others. If you don’t have a lot of financial or legal knowledge, it can seem like sifting through a pile of confusing nonsense.
Don't let bill collectors convince you that you are ineligible for bankruptcy. Debt collectors do not want you to file bankruptcy under any circumstances because it means that they will not get the money you owe them, so they will always tell you that you do not qualify when given the chance. The only way to truly know if you qualify is to do some research or speak with a bankruptcy attorney.
Take some time each day to stop thinking about your bankruptcy. It can seem like a thought you cannot get out of your head, but it is important to step away from the situation before you become too upset. Not only that, but removing it from your thoughts allows you to bring a fresher, more optimistic perspective to the table when you take up the subject again.
Don't let bill collectors convince you that you are ineligible for bankruptcy. Debt collectors do not want you to file bankruptcy under any circumstances because it means that they will not get the money you owe them, so they will always tell you that you do not qualify when given the chance. The only way to truly know if you qualify is to do some research or speak with a bankruptcy attorney.
Look for a bankruptcy attorney that belongs to the NACBA (The National Association of Consumer Bankruptcy Attorneys). When you are filing for bankruptcy, it is essential that you hire the services of an experienced and reputable bankruptcy attorney. Attorneys that are members of the NACBA, are also, members of a well-respected consumer bankruptcy organization, so you can be sure that you will be getting the best legal advice available.
If you have student loan debt, you'll need to prove that paying your student loans would constitute an undue hardship in order to get it discharged. Gather visit the up coming website of your financial documents and draw up two budgets: one that includes student loan payments and one that does not. That way you can more easily demonstrate that paying your student loans would interfere with your financial recovery.
It is important that you don't let bankruptcy get you down in the dumps. Bankruptcy can be a challenging time in anyone's life, but it is meant to give you a fresh start, enabling you to establish good credit and move toward a better future for you and your family. Remember, bankruptcy is your legal right, so don't feel guilty or ashamed of taking advantage of it. If you do feel that you are suffering excess anxiety or depression over financial issues, counseling may help you to better deal with your emotions and concerns.
Ask friends and family for moral support. They may not be able to lend you money, but you should be able to tell them about your hardships and to lean on them. It can be hard to talk about money with the people close to you. You will likely find that they are much more supportive than you expect.
A great personal bankruptcy tip is to consider what kind of bankruptcy you'd like to go for. In general, chapter 13 is much better because it doesn't taint your credit report. It allows you to hold on to most of your belongings. Chapter 7 is much more extreme to file for.
When you are about to file for bankruptcy, be sure you have all the financial information at hand. Even things that you do not use, should be listed in a bankruptcy filing. These could include, income from even small jobs, any vehicles listed in the filer's name whether or not they use them, and any pending lawsuits.
Avoid running up your debt limit before you file for bankruptcy. Judges, and creditors look at recent history along with your current situation. A judge can deny some of your debts from being wiped out if, they think you're just taking advantage of the system. Try to show that that you're willing to change your fiscal habits.
Stay on top of your finances enough to file before the last possible moment. Your financial debt, and responsibilities will not solve themselves, nor will they be able to sit on the back burner forever. You must act decisively. Through knowledge of where your finances truly stand. Ignoring the problem will only result in greater issues.
Clean up your credit record after ten years. When you file Chapter 7 bankruptcy, it remains on your credit report for ten years. However, the credit bureaus are not required to remove the information. In order to get rid of the bankruptcy record, write a letter to the credit reporting agencies, along with a copy of your discharge notice. Follow https://www.thehindubusinessline.com/economy/logistics/creditors-panel-approve-jnpts-bid-to-buy-debt-laden-dighi-port/article26162798.ece up with a phone call to make sure that they have removed the bankruptcy record.
Get the details. After filing for personal bankruptcy, you are still obligated to pay your personal bills. The collection letters and some monthly bills will stop coming, but you are still required to pay them off. This means that even if you don't receive a bill to your house, it doesn't mean that you're off the hook!
No matter how trivial you may think it is, all income should be reported in your bankruptcy filing. You can create issues in your bankruptcy if your income information does not flush with bank and finance records. Be sure to include all incomes within the household that can be considered part of your normal income.
Many people think that they can save a lot of money by filing bankruptcy themselves and trying to handle their case without the aid of an attorney. This isn't wise for several reasons. There are up to 50 pages of paperwork to fill out, filings and laws that you may not know about. An attorney will know how to handle your case and will surely save you money by negotiating with your creditors.
Work with a reputable credit counseling agency. If you have decided to file for bankruptcy, work with a credit counseling agency that has the approval of the US Trustee's Office. They will provide a 90 minute mandatory counseling session, after which they will determine if you qualify for a Debt Management Plan. They will also issue you with a certificate that allows you to file for bankruptcy.
Avoiding bankruptcy is all about planning. Once you plan things out and execute your plan, you make sure that you are financially secure, no matter what comes up. Proper planning is key to making sure you are not stressed in life. Apply these tips to your life, so that you do not have to file for bankruptcy ever again.
Replies